

Have you ever been out to a great dinner, or on a great vacation, or perhaps at a great show, really enjoying yourself, yet knowing in the back of your mind that the bill for this great experience would come due, and it might be a doozy? Think about that experience and feeling, apply it to today’s markets, and ask yourself: how will investors feel when it’s time to pay the bill?
We’re not writing this to imply that a market crash akin to the Financial Crisis is just around the corner; far from it. We see ourselves in a slow-growth world that is a result of the experimental monetary policy by governments and central banks (CBs). They are manipulating interest rates without providing comparable fiscal stimulus to recover from a financial downturn, and as a result, these easy rate policies around the globe have lulled investors into a false sense of complacency.
Just looking at this small sampling of market returns gives us some idea about the effects of the CB’s policy of low rates:
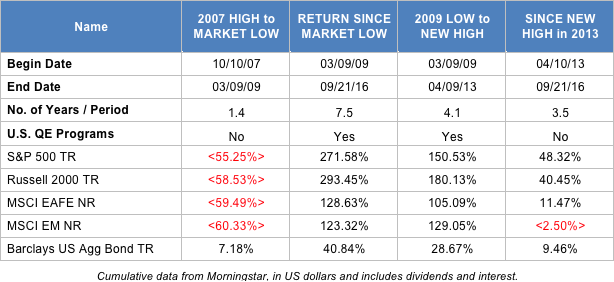
During the period when the U.S. Fed embarked upon its Quantitative Easing programs (QE) and Operation Twist, the stock and bond markets earned much of the total returns since the low of the Financial Crisis. Other central banks, particularly in Europe, chose different paths that focused initially on austerity and had less robust results (e.g. a ‘double-dip’ recession in the U.K.). Across the globe, however, it appears that the ability for continued monetary policy stimulus to drive growth is limited. We are left with stagnant growth levels, negative interest rates in many countries, market uncertainty and growing populist movements that promote nationalism over growth.
Central banks are not united in policy goals, governments and corporations are not engaging in enough (if any) fiscal stimulus, and the world’s growth engine for many years—China—is retrenching and transforming. All of this leads to a suspicion that stocks and bonds are overpriced, particularly on the part of income-seekers driving money into utilities and other high-dividend stocks. This is clearly an important inflection point. We must accept that issues that have become political ‘hot button’ talking points—global trade, immigration policy, tax reform and populism—are perhaps now more important drivers of future growth than furthering the low interest rate policies that have dominated the past seven years.
Investors have asked us, are we worried about a bear market? A combination of several indicators turning bearish would cause us concern, such as much higher interest rates and inflation, an inverted yield curve and stock overvaluation. Recent market gyrations seem to be overreactions at this point; U.S. economic data do not currently predict a recession or an inflationary environment that would require the Fed to quickly raise rates. This does NOT mean valuations are at relative discounts—low rates are pushing some investors to equities, and areas such as utilities will be the first to sell off as rates move.
We’re seeing a lot of investment suggestions for private equity, private or second-market debt funds, real assets and options-hedged equity products. All are expected to provide better risk-adjusted returns than conventional stocks and bond portfolios. Our evidence doesn’t support many of these ideas. As we learned eight years ago, and can see in the table above, the traditional relationships between stocks and bonds provides the insurance and low correlation we need. In times of crisis, U.S. Treasurys and public-market liquidity (such as U.S. large-cap equities) are the prized investments.
Our clients know, too, that we preach diversification, patience and a focus on the far horizon, not the next step. The market data we review indicate that the U.S. economy is still healthy (but not robust), and few signs of the high rates, high inflation, excessive stock valuations or a recession are present. We expect some volatility in the period ahead, but our long-term growth outlook remains positive.
federal reserve interest rates monetary policy stock market